Selling a home in Lynden, Ferndale, Blaine, Birch Bay, or Everson and buying your next one? You’ve probably heard the advice to rent for a while and hold out for lower mortgage rates. But when your down payment is a set amount of equity from the home you just sold, waiting can quietly work against you.
Here’s a plain-English look at why.
1. Where Rates and Prices Stand Right Now
Freddie Mac’s weekly survey put the average 30-year fixed rate at 7.32% for the week of October 22, 2026, down from 7.40% a week earlier. Fannie Mae’s October 2026 Housing Forecast has the rate averaging 7.4% this quarter and 7.5% through 2027.
On prices, the 100-plus experts in Fannie Mae’s Q3 2026 Home Price Expectations Survey expect national gains of 2.2% in 2027 and 2.7% in 2028. Closer to home, the median closed price for single-family homes across Whatcom County was $620,250 in September, according to NWMLS data.
2. Why a Fixed Down Payment Changes the Math
Waiting is a trade: pay more for the house later in exchange for a lower rate. That trade changes when your cash is capped. If prices rise while you wait, the same down payment covers a smaller share of the home, so your loan gets bigger. Drop below 20% down and you’ll likely pay private mortgage insurance (PMI) too.
3. A Side-by-Side Example
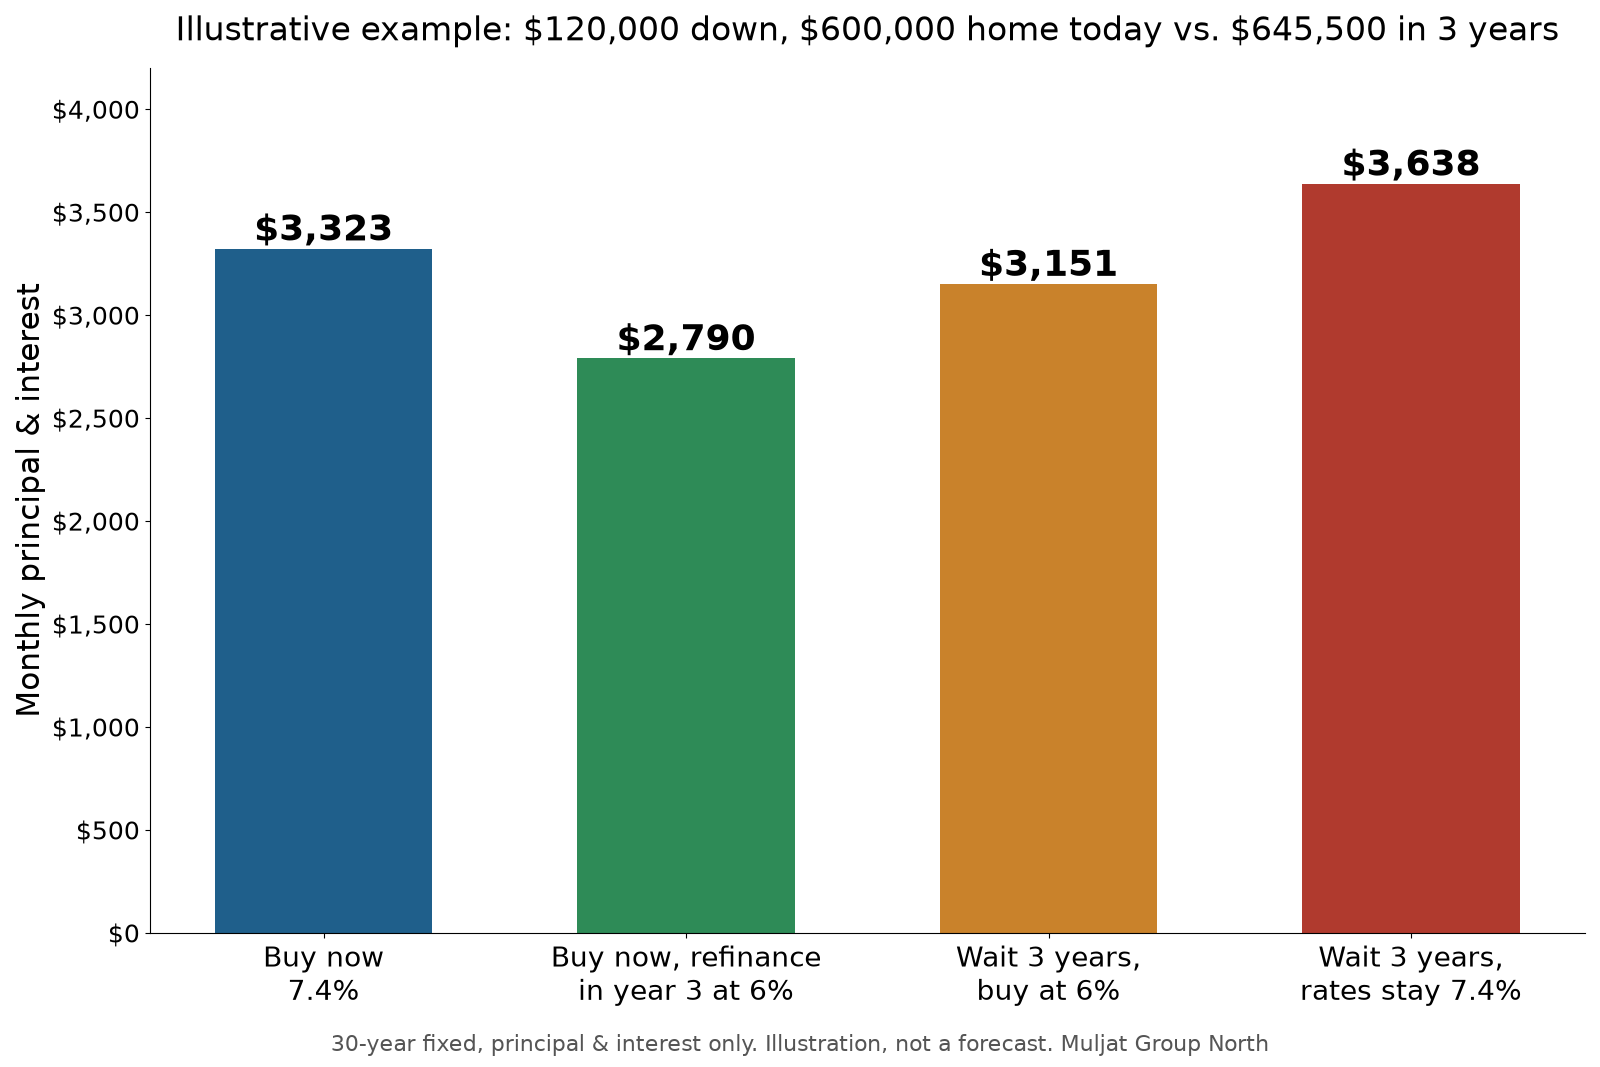
Here’s an illustration with round numbers, not a forecast. Say your sale leaves you with $120,000, exactly 20% of a $600,000 home. The rate is 7.4%, close to today’s average. Over three years the home’s value climbs about 7.6% to $645,500, in line with the expert survey’s range. Then, in the hopeful case, rates fall to 6%.
| Path | Home price or value | Loan | Rate | Monthly P&I | Equity after 3 years |
|---|---|---|---|---|---|
| Buy now | $600,000 | $480,000 | 7.4% | $3,323 | about $180,100 |
| Buy now, refinance in year 3 | $645,500 | $465,400 balance | 6.0% | $2,790 | about $180,100 |
| Wait 3 years, then buy | $645,500 | $525,500 | 6.0% | $3,151 | $120,000 |
| Wait 3 years, rates don’t fall | $645,500 | $525,500 | 7.4% | $3,638 | $120,000 |
P&I is principal and interest on a 30-year fixed loan. Property taxes, insurance and any PMI are extra. Equity is the home’s value minus the loan balance, before selling costs.
4. What the Numbers Are Telling You
- If rates fall to 6%: after refinancing, the buy-now household pays about $360 a month less than the household that waited. It also has roughly $60,000 more equity, from about $14,600 of principal paydown plus appreciation.
- If rates stay near today’s level: waiting looks even worse. The waiter borrows more at the same rate and pays about $315 a month more than the buy-now payment.
- If prices fall instead: the picture can flip. In this example, a 5% price drop combined with 6% rates would give the waiter the lower payment. Prices aren’t climbing everywhere locally, either. Lynden’s September median closed price was $589,000, down 4.2% from a year earlier, per NWMLS, though that’s a small one-month sample.
5. The Fine Print Before You Decide
- Refinancing costs money. Closing costs often run about 1% to 3% of the loan. Dropping from $3,323 to $2,790 saves about $533 a month, so $4,700 to $14,000 in costs takes roughly 9 to 26 months to earn back.
- A refinance isn’t guaranteed. It depends on rates actually falling and on you qualifying again.
- Plan for the higher payment. You’ll want steady income and reserves to carry today’s payment for a few years.
- Life counts too. Buying now ends the rent checks or temporary housing and gets you settled sooner.
Final Thoughts: Run Your Own Numbers
When the equity from your sale covers 20% of today’s price, holding out for a better rate often means a bigger loan and less equity down the road. Buying now and refinancing if rates improve can make today’s rate a temporary cost rather than a permanent one. It isn’t risk-free, and your town and timeline matter.
This example is for illustration only. It isn’t a forecast or financial advice. Talk with a licensed mortgage lender about rates and refinancing, and with a tax advisor about how interest, property taxes and your sale affect you.
Selling one home and buying the next? Reach out to Muljat Group North. We will run these numbers with your actual sale proceeds, price range and town so you can see which path fits.